jaquelinegreen
About jaquelinegreen
How To Use Homes To Desire
 There is a version of the housing market story that gets told over and over, and it goes like this: prices are high, rates are high, nothing is affordable, and the only people buying are the ones with cash. That version is not wrong, exactly. It is just incomplete.
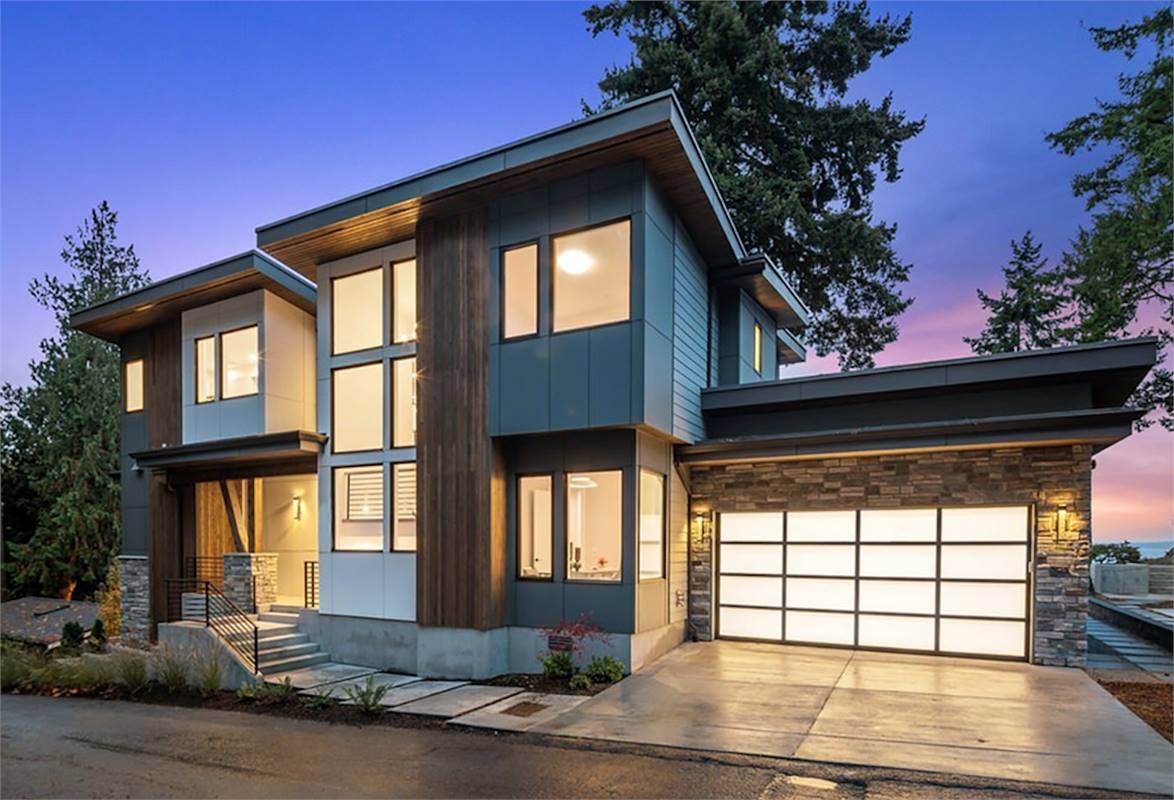 The arithmetic here is brutal and worth understanding clearly. A buyer who financed a $400,000 home at three percent in 2021 pays roughly $1,686 per month on principal and interest. That same loan at a seven percent rate costs $2,661. The difference between those two payments explains why so many potential sellers are sitting tight. Volume collapsed. Prices mostly did not.
Here is what that creates for someone with solid credit and a real pre-approval in hand: more room to negotiate than the market’s reputation suggests. The panic buyers are gone. The buyers who showed up with emotion instead of analysis have mostly sat back down. What remains is a more functional market, even if it is not a cheap one.
 Your credit score affects your rate more directly than most buyers realize. Moving your score up by 40 points before you apply can be worth more than months of rate watching. If your score has room to improve, give yourself three to six months to work on it before you begin in earnest.
 If the report surfaces problems that go well beyond normal wear and tear, you have three options, not one, and walking away is a legitimate one of them. You can walk away if the scope of the problems makes the agreed price no longer reasonable. The one thing to avoid is accepting everything uncritically because you are afraid of losing the deal.
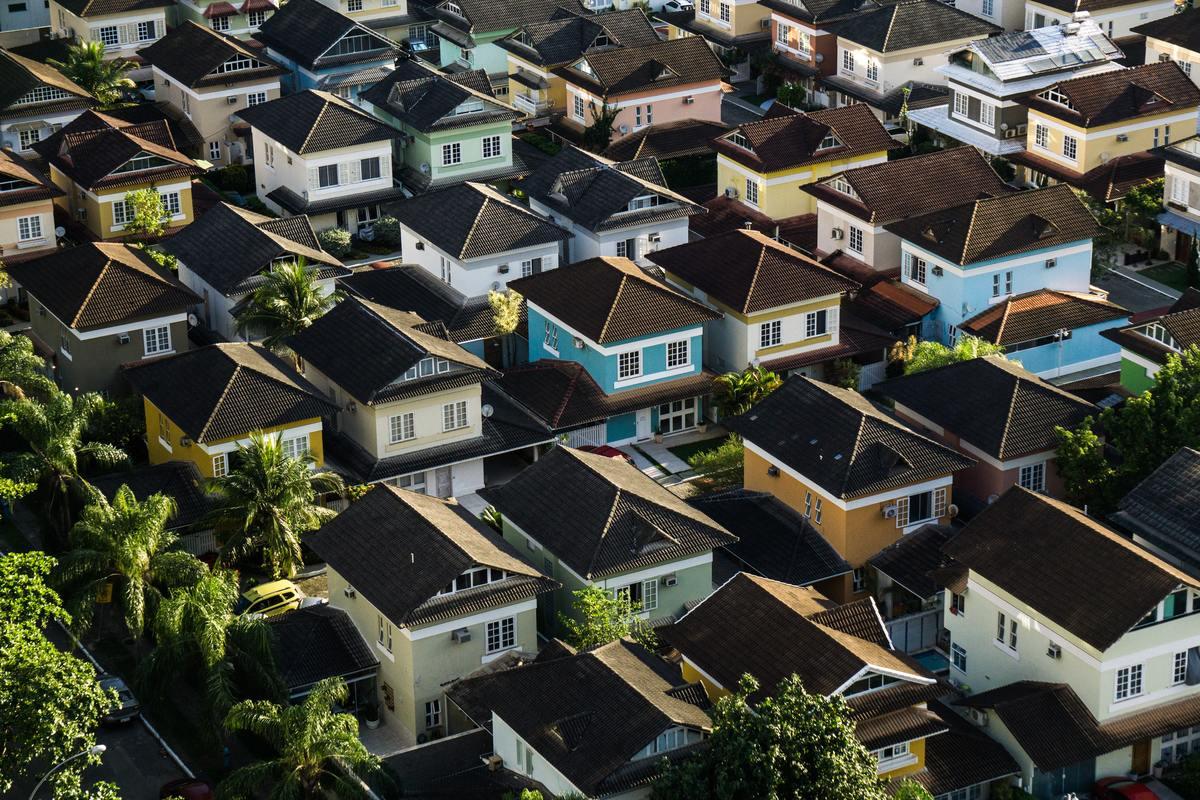 Budget enough to cover origination fees, title, escrow, prepaid taxes, and insurance without being caught short at the table. First-time buyers are sometimes surprised by how much cash is required beyond the down payment itself. Ask your lender for a Loan Estimate as early in the process as possible.

Real estate rewards preparation more than it rewards timing. Waiting for a better market is a reasonable position only if your personal situation supports it, otherwise you are just paying rent while prices hold. A look at real estate listings and pricing data in your target area costs nothing and tells you a great deal.
No listing found.